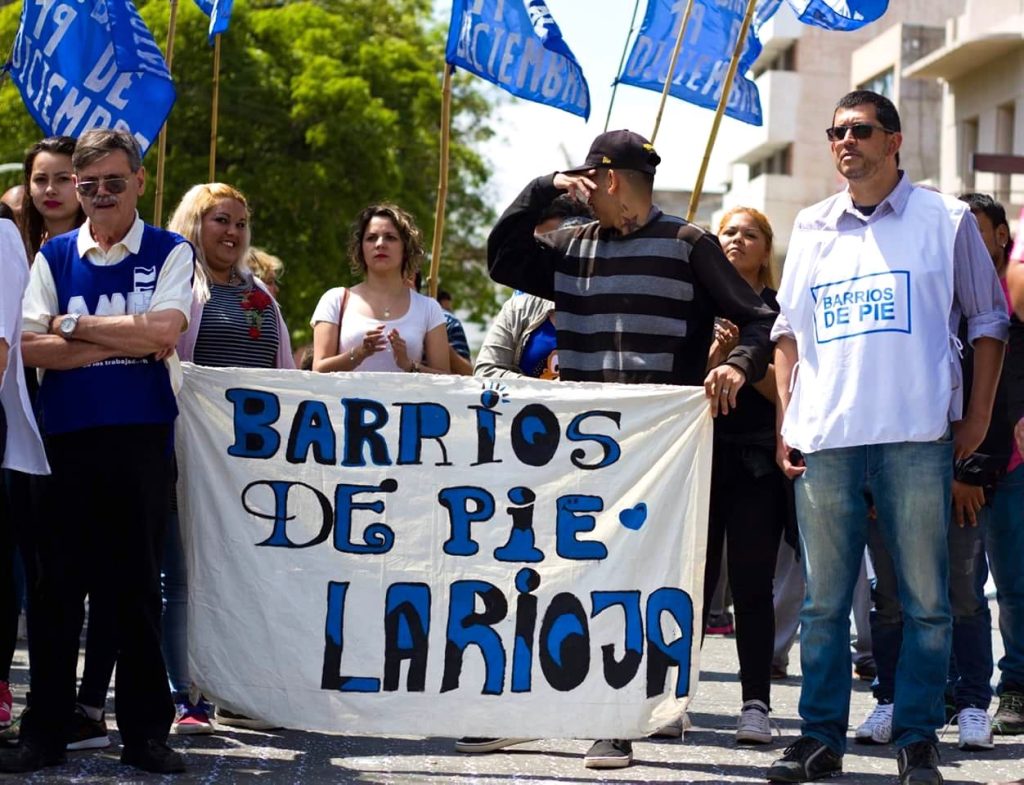
Libres del Sur has begun developing a proposal in La Rioja to limit collection practices it considers abusive toward indebted individuals and families. Lucas de la Fuente said the work is being carried out with legal advice and that no final bill has yet been filed or enacted. Its declared purpose is not to cancel obligations or prevent creditors from claiming payment, but to require collection to respect privacy, reasonable hours and the debtor's dignity. That distinction will be central to any future regulation.
The initiative begins with an everyday economic diagnosis. De la Fuente described households whose income no longer covers food, services and fuel, forcing them to use cards, loans, store credit or multiple jobs. When one obligation is paid with another, debt stops being a temporary tool and becomes a difficult chain. Interest rates, late fees and falling purchasing power deepen the problem, while non-payment exposes people to increasingly insistent collection systems.
The activist estimated that more than five million people are in arrears and associated that figure with a situation affecting roughly one in four Argentines. Those numbers formed part of his assessment and require clarification of the population measured, the type of credit and the period. Arrears may mean delays beyond three months, but databases do not all use the same definition. Serious regulation will need comparable statistics distinguishing occasional delay, persistent over-indebtedness and insolvency.
The practices behind the proposal are concrete: calls in the early hours, repeated messages, threats of consequences not provided by law and contacts with relatives, neighbours or employers. De la Fuente said these actions seek emotional pressure and may damage employment and personal relationships. Disclosing a debt to third parties also compromises confidentiality. Legitimate collection allows communications and payment proposals, but loses legitimacy when it relies on intimidation, public humiliation, misleading information or a frequency that persistently disrupts daily life.
The organisation is studying how to adapt its ideas to current law and which authority would enforce them. Possible tools include time limits, mandatory identification of collection agencies, bans on third-party contact, communication logs and simple complaint channels. Clear information on principal, interest, fees and ownership of the debt would also be necessary. The challenge is to create verifiable rules: a general statement against harassment is weak unless it defines conduct, sanctions, available evidence and a supervisory body.
De la Fuente acknowledged that national measures aimed at lowering interest rates could reduce refinancing costs for some debts, but said they do not address the origin of the problem. Cheaper credit may ease future instalments; it does not restore eroded income or erase accumulated balances. The benefit also depends on debtors retaining access to formal terms instead of being pushed toward riskier lenders. An economic response must combine prevention, information, restructuring mechanisms and protection against unlawful practices.
In La Rioja, the political organisation offers guidance to people receiving demands and seeks to turn those cases into evidence for a broader proposal. That work may reveal patterns, but it must preserve documentation and avoid promising outcomes no organisation can guarantee. Not every call is harassment and not every debt can be renegotiated under the same terms. A useful tool should explain when to contact consumer protection, when professional advice is needed and how to preserve messages, numbers, times and receipts without exposing personal data.
The next step is to finish the text, determine whether action belongs at provincial, municipal or national level and file it with the competent authority. Until then, this is a developing proposal, not protection already in force. Its quality will depend on balancing rights: enabling documented collection, offering pathways for debtors and excluding methods that turn an economic obligation into personal persecution. With arrears widespread, legal precision will be as important as the social diagnosis that launched the debate.


